
Many individuals may not realize that having secondary insurance can significantly reduce your out-of-pocket costs for preventive medical care. This additional policy works alongside your primary insurance to cover services such as routine check-ups, vaccinations, and screenings that are important for early disease detection and maintaining your health. By opting for secondary insurance, you can enhance your healthcare experience, ensuring that financial barriers do not hinder your access to these vital services. Understanding how this coverage functions can empower you to make informed decisions about your health.
Understanding Secondary Insurance
A secondary insurance policy acts as a supplemental layer of coverage that can help cover additional medical expenses after primary insurance has been applied. This coverage can ease the financial burden of out-of-pocket costs for preventive care and other medical services. (Considering your healthcare needs, choosing the right policy can be an important decision.)
Definition and Scope
One of the key aspects of secondary insurance is its definition; it typically serves to cover costs that are not fully paid by your primary insurance. This may include deductibles, copayments, or even services not covered by the primary plan. It extends your financial safety net in managing healthcare costs.

Types of Secondary Insurance
Any type of secondary insurance can provide particular benefits tailored to your healthcare situation. Here are some common forms:
- Medigap Policies: Supplemental plans for Medicare beneficiaries.
- Employer-sponsored Plans: Additional coverage provided by employers.
- Health Savings Accounts (HSAs): Savings accounts for medical expenses.
- Accident Insurance: Coverage specifically for accidents.
- Cancer Insurance: Specialized plans for cancer treatment.
The right choice can enhance your health benefits portfolio.
| Type | Description |
| Medigap | Supplement for Medicare expenses. |
| Employer-sponsored | Company-provided additional coverage. |
| HSAs | Tax-advantaged medical savings accounts. |
| Accident Insurance | Specific coverage for injuries from accidents. |
| Cancer Insurance | Targeted plans for cancer-related expenses. |
With exploring types of secondary insurance, you may discover various options that fit your healthcare needs. Each type comes with its own set of benefits that can significantly reduce out-of-pocket expenses.
- Individual Plans: Tailored policies to cover personal needs.
- Family Plans: Coverage for all family members.
- Short-term Insurance: Temporary plans during transitions.
- Specialized Coverage: Focused on specific conditions or treatments.
- Global Health Insurance: Coverage for international health needs.
The options are abundant, so review each thoroughly to make the best decision for your health coverage.
| Type | Description |
| Individual Plans | Designed for personal healthcare needs. |
| Family Plans | Comprehensive plans for entire families. |
| Short-term | Temporary insurance during life changes. |
| Specialized | Plans for particular medical conditions. |
| Global Insurance | Coverage for healthcare abroad. |
The Role of Secondary Insurance in Preventive Care
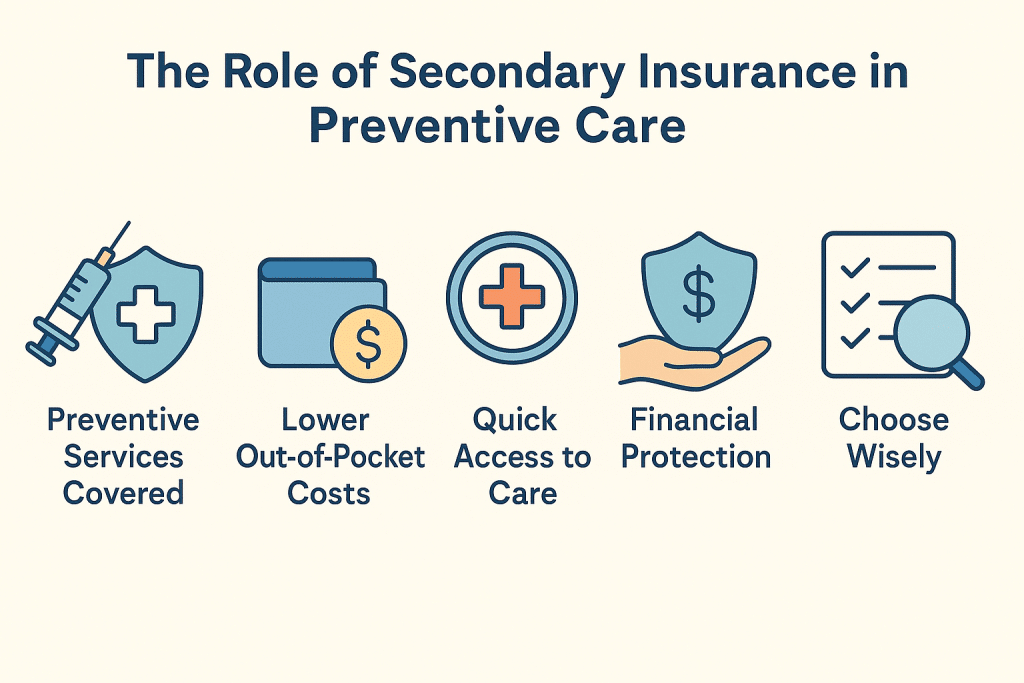
The inclusion of secondary insurance can significantly enhance your access to preventive medical care. Often, primary insurance plans have limitations, and secondary coverage can bridge those gaps, reducing your out-of-pocket costs for necessary services. (Choosing the right secondary insurance is vital to maximizing your preventive care benefits.)
Coverage of Preventive Services
Services deemed preventive, such as annual check-ups or vaccinations, typically receive enhanced coverage from secondary insurance plans. This not only increases your access to necessary care but also ensures you stay healthy without the worry of substantial out-of-pocket expenses.
Impact on Out-of-Pocket Expenses
For many individuals, the financial burden of out-of-pocket expenses for preventive care can feel overwhelming. However, having secondary insurance mitigates this burden by covering a greater portion of the costs associated with services that keep you healthy.
A growing number of studies indicate that individuals with secondary insurance save significantly on their out-of-pocket expenses for preventive care compared to those who rely solely on primary insurance. This added coverage not only helps in routine check-ups and screenings but also allows you to access specialized preventive treatments at a lower cost, ensuring that financial barriers do not prevent you from maintaining your health. Investing in secondary insurance is a wisdom that can lead to improved health outcomes and overall well-being.
Benefits of Having Secondary Insurance
Clearly, having secondary insurance can significantly enhance your overall healthcare experience. This type of coverage often extends beyond your primary plan, helping to cover co-pays, deductibles, and additional services that might not be fully funded otherwise. By adding this layer of protection, you can alleviate the financial burden of medical expenses, ensuring that you seek necessary preventive care without hesitation. (Choosing the right secondary insurance can greatly influence your ability to access quality care.)
Enhanced Access to Care
Against a backdrop of rising healthcare costs, secondary insurance can provide you with the ability to promptly receive necessary treatments. With this additional coverage, you’re less likely to delay preventive services that keep you healthy, as it can help reduce out-of-pocket expenses that often deter individuals from seeking care.
Financial Protection and Savings
Savings on healthcare costs can be substantial when you have secondary insurance. With increased coverage, you can minimize the financial impact of medical visits, tests, and treatments.
In addition, secondary insurance can offer you financial protection by covering expenses that your primary plan might not, such as specialized treatments or out-of-network services. This means that if you encounter high medical costs, your secondary coverage can step in to share the financial burden, safeguarding your savings and making healthcare more affordable. Ultimately, this dual-layer of coverage may give you the peace of mind needed to prioritize your health without fear of overwhelming out-of-pocket expenses.
Choosing the Right Secondary Insurance Plan
For selecting a secondary insurance plan, it’s important to assess your specific healthcare needs and consider how they align with the coverage provided. This includes evaluating whether the plan supplements your primary insurance effectively, especially for preventive care costs, co-pays, and out-of-pocket maximums. (Understanding available options is key to getting the best value.)
Key Considerations
By taking into account factors like coverage limits, network providers, and premium costs, you can make a well-informed decision. Pay attention to any exclusions or waiting periods to ensure you choose a plan that provides adequate protection for your health needs. (Assessing the overall financial impact will guide your choice.)
Comparing Different Options
At the heart of choosing a secondary insurance plan is the process of comparing various options available in the market. It helps to create a chart that lists benefits, costs, and coverage specifics for easy visualization. This way, you can quickly identify which plans deliver the most value in line with your preventive care requirements. (Gather all necessary information before making a decision.)
Comparison Table
| Plan Features | Details |
|---|---|
| Monthly Premium | Varies by plan |
| Deductible | Check how much you need to pay before coverage kicks in |
| Co-payment Amount | Costs for preventive services and doctor visits |
| Network Providers | Ensure your preferred healthcare providers are included |
Even with comprehensive options available, prioritizing your health while looking for secondary insurance will direct your choices effectively. Consider factors like out-of-pocket costs versus the services provided, as this can significantly affect your long-term healthcare expenses. A focused approach allows you to secure the best supplementary coverage tailored to your preventive care needs.
Benefits Table
| Benefit Type | Description |
|---|---|
| Reduced Out-of-Pocket Costs | Secondary insurance often helps lower the expenses not covered by the primary plan. |
| Access to a Wider Network | Some plans provide access to a larger array of service providers. |
| Enhanced Preventive Care Coverage | Often includes additional screenings or exams that primary plans may not cover. |
Common Misconceptions
Keep in mind that many people hold misconceptions about secondary insurance that can affect their healthcare decisions. Some believe secondary insurance is unnecessary if they already have primary coverage, while others think it only covers specific types of care. (Understanding your options is vital to maximizing your benefits.)
Myths About Secondary Insurance
Before submerging into secondary insurance, you may encounter myths that can sway your perception. Many people think that secondary insurance is always too costly or provides minimal additional coverage. (Assessing your healthcare needs can help in choosing the right plan.)
Clarifying Misunderstandings
Among the various misunderstandings, one common belief is that secondary insurance is only for those with chronic illnesses or high medical expenses. In reality, it can be beneficial for anyone looking to alleviate out-of-pocket costs for routine visits and preventive care. (Evaluating your health situation and potential expenses is important in making an informed decision.)
Another point of clarity is that secondary insurance can significantly enhance your primary coverage, rather than complicate it. This type of insurance not only helps in lowering your costs but can also expand your access to services not fully covered by your primary plan. By understanding the true scope of what secondary insurance offers, you can make choices that protect your health and finances better. (Finding the right secondary insurance can ultimately lead to improved health outcomes.)
Case Studies: Real-Life Impact
Not only does secondary insurance assist in covering costs, but it also significantly enhances access to preventive medical care. Here are some case studies illustrating its impact:
- Case Study 1: Family of four saved $2,500 annually on preventive screenings.
- Case Study 2: A diabetic patient reduced out-of-pocket costs for annual check-ups by 60%.
- Case Study 3: An elderly couple maintained preventive medications at a 75% lower out-of-pocket cost.
- Case Study 4: A young professional attended wellness visits 5 times more frequently with coverage.
Success Stories
With the right secondary insurance plan, you can enjoy life-enhancing preventive care without feeling financial strain. By prioritizing your health through affordable access, you empower yourself for a healthier future.
Testimonials from Consumers
Stories from consumers showcase the transformative power of secondary insurance. (Your health is worth the investment.) By sharing their journeys, you gain insights into how this type of coverage has eased their financial burden while accessing preventive services.
Consumers have expressed relief and gratitude, highlighting how secondary insurance made vital screenings and vaccinations accessible, leading to better health outcomes. (Taking action to secure the right coverage can change your health trajectory.) Many share that they’ve been able to prioritize their health, visiting doctors without hesitance and benefiting immensely from early detection and prevention strategies.
Conclusion
To wrap up, secondary insurance can significantly ease your financial burden when it comes to preventive medical care. By providing additional coverage, it allows you to access necessary health services without the worry of hefty out-of-pocket expenses. This ensures that you stay on top of your health needs, making it easier for you to seek preventive measures that can lead to better health outcomes. Make sure to explore your options to find a secondary insurance plan that best fits your unique health requirements.
FAQ
Q: What is secondary insurance and how does it relate to preventive medical care?
A: Secondary insurance is an additional health insurance policy that helps cover costs not fully paid by a primary insurance plan. It can help consumers reduce out-of-pocket expenses for preventive medical care services, such as annual check-ups, vaccinations, and screenings, thus improving access to crucial health services.
Q: What types of preventive medical care are typically covered by secondary insurance?
A: Secondary insurance commonly covers a range of preventive medical services, including routine physical exams, immunizations, mammograms, colonoscopies, and other screenings recommended by healthcare providers. Coverage may vary by plan, so it’s important for consumers to review their specific policy for details on what services are included.
Q: How can having secondary insurance impact out-of-pocket costs for preventive services?
A: With secondary insurance, consumers may benefit from reduced co-pays, deductibles, or co-insurance for preventive services. This means that when they receive care, the secondary insurance can help cover what the primary insurance does not, leading to lower overall health care costs for patients and making preventive care more affordable.
Q: Are there any eligibility requirements for secondary insurance coverage of preventive medical care?
A: Eligibility requirements for secondary insurance can vary by insurer, but generally, individuals must have an active primary health insurance plan. Additionally, some secondary insurers may have specific guidelines regarding which types of preventive care are eligible for coverage, so it’s advisable to check with the insurer for any necessary conditions.
Q: How do consumers find out if their secondary insurance covers preventive care and what steps should they take?
A: Consumers can start by reviewing their secondary insurance policy details, which will outline covered services. They can also contact the insurance provider’s customer service for clarification on coverage for specific preventive services. Additionally, consulting with healthcare providers can help clarify which services will be covered under both primary and secondary insurance plans.

Paul Kohn MBA is a seasoned business consultant known for helping businesses maximize tax credits and incentives to fuel growth and profitability. He holds a Master’s in Business Administration and has helped numerous companies secure millions in tax credits and implement effective business strategies. He is regarded as a trusted authority for business owners seeking to optimize their savings and growth.